Markets Overview:
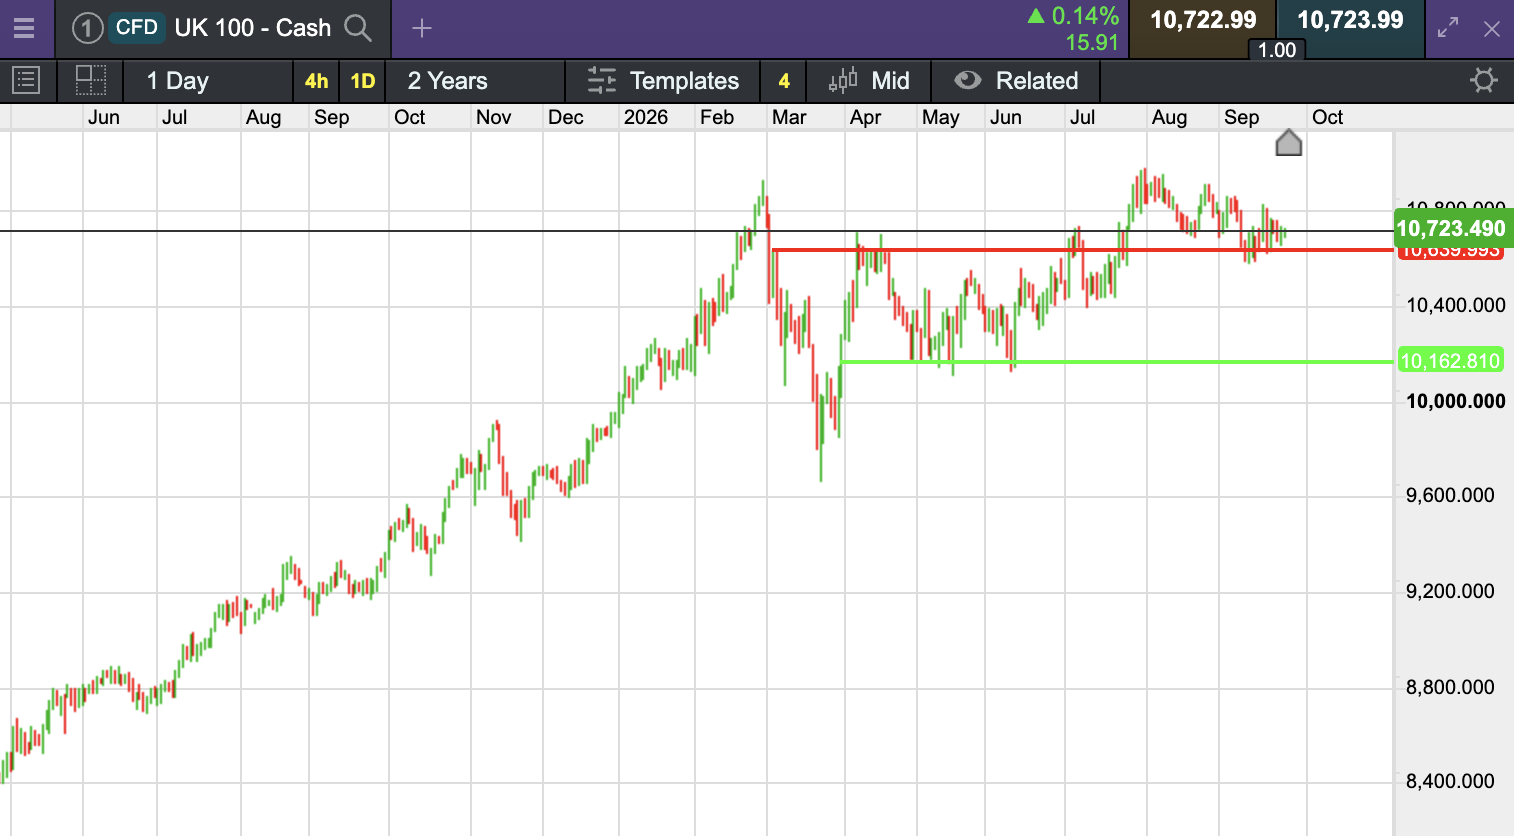
The UK 100 is called to open +40 points at at 10,719. The FTSE 100 is expected to open higher on Friday as retreating oil prices offer some relief from inflation concerns and UK consumer confidence improves.
Wall Street ended Thursday’s session little changed but under the surface investors were pulled two ways. The S&P 500 slipped 1.90 points (−0.02%) to 7,704.13 and the Dow fell 161.61 points (−0.31%) to 51,349.98, while the Nasdaq Composite eked out a fractional gain of 3.34 points (+0.01%) to 26,939.37. Rising bond yields were the main headwind — the US 10-year Treasury yield pushed up to around 5.10–5.14%, its highest since 2007, and the 30-year touched 5.43%, a 2004 high. Offsetting that, oil jumped over 3% on hopes of a phased US–Iran deal to reopen the Strait of Hormuz, and sentiment was helped by reports of progress on extending the US–China trade truce around the Trump–Xi summit.
Overnight, Asia was mixed: Japan’s Nikkei 225 extended its rally, up around 1.3% to near 66,350 (a fifth straight gain), while Hong Kong’s Hang Seng fell about 1.7% to roughly 24,330 (a third straight loss) as the global bond sell-off weighed on sentiment. Australia’s ASX 200 was down around 0.7%, tracking Wall Street’s losses and the oil price surge, and China’s Shanghai Composite lost 1.2% on Thursday amid lingering uncertainty over the US–China trade truce extension. South Korea’s KOSPI stayed shut for the Chuseok holiday through Friday; its last print was Wednesday’s close of 7,081 (+0.9%).
In the UK/Europe today, the calendar is light: no Bank of England MPC meeting this week or next, though Governor Andrew Bailey speaks at an Oxford/New York Fed monetary economics conference; the Fed’s next FOMC decision is not until 27–28 October (it last met 15–16 September) and the ECB’s next meeting is 28–29 October. UK GfK consumer confidence hit a more-than-two-year high in September, released Thursday.
Company News & Broker Comments:
Company News:
Reporting Today:
UK
No noteworthy announcements
US
No noteworthy announcements
Reporting Tomorrow:
UK
Tullow Oil (TLW) – Half Year Results
US
No noteworthy announcements
In Focus Today:
| Time (UK) |
Event |
Consensus |
Prior |
| All day |
South Korea (KOSPI) closed for Chuseok holiday |
— |
— |
| No scheduled UK data |
UK economic calendar is empty today per Trading Economics |
— |
— |
| 10:15 |
Fed’s John Williams speaks |
— |
— |
| 13:30 |
US Durable Goods Orders MoM (Aug) |
~−0.4%* |
— |
| 13:30 |
US Durable Goods ex-Transport MoM (Aug) |
~+0.6%* |
— |
| 14:20 |
Fed’s Jeffrey Schmid speaks |
— |
— |
| 15:00 |
US Michigan Consumer Sentiment, final (Sep) |
~51.7* |
— |
| ~14:00 (tbc) |
BoE Governor Andrew Bailey speaks at Monetary Economics Conference (with Oxford/NY Fed) |
— |
— |
Next Week’s Ex-Dividends:
UK 100 companies going ex-dividend on 1st October 2026:
British American Tobacco
Smith & Nephew
Weir Group
F&C Investment Trust
UK 250 companies going ex-dividend on 1st October 2026:
Wickes Group
TP ICAP Group
Breedon Group
Kainos Group
Hunting
Morgan Sindall Group
Bodycote
Travis Perkins
For any help you may require placing trades or in terms of market information, put a call in to our trading floor – it’s all part of the service.