Markets Overview:
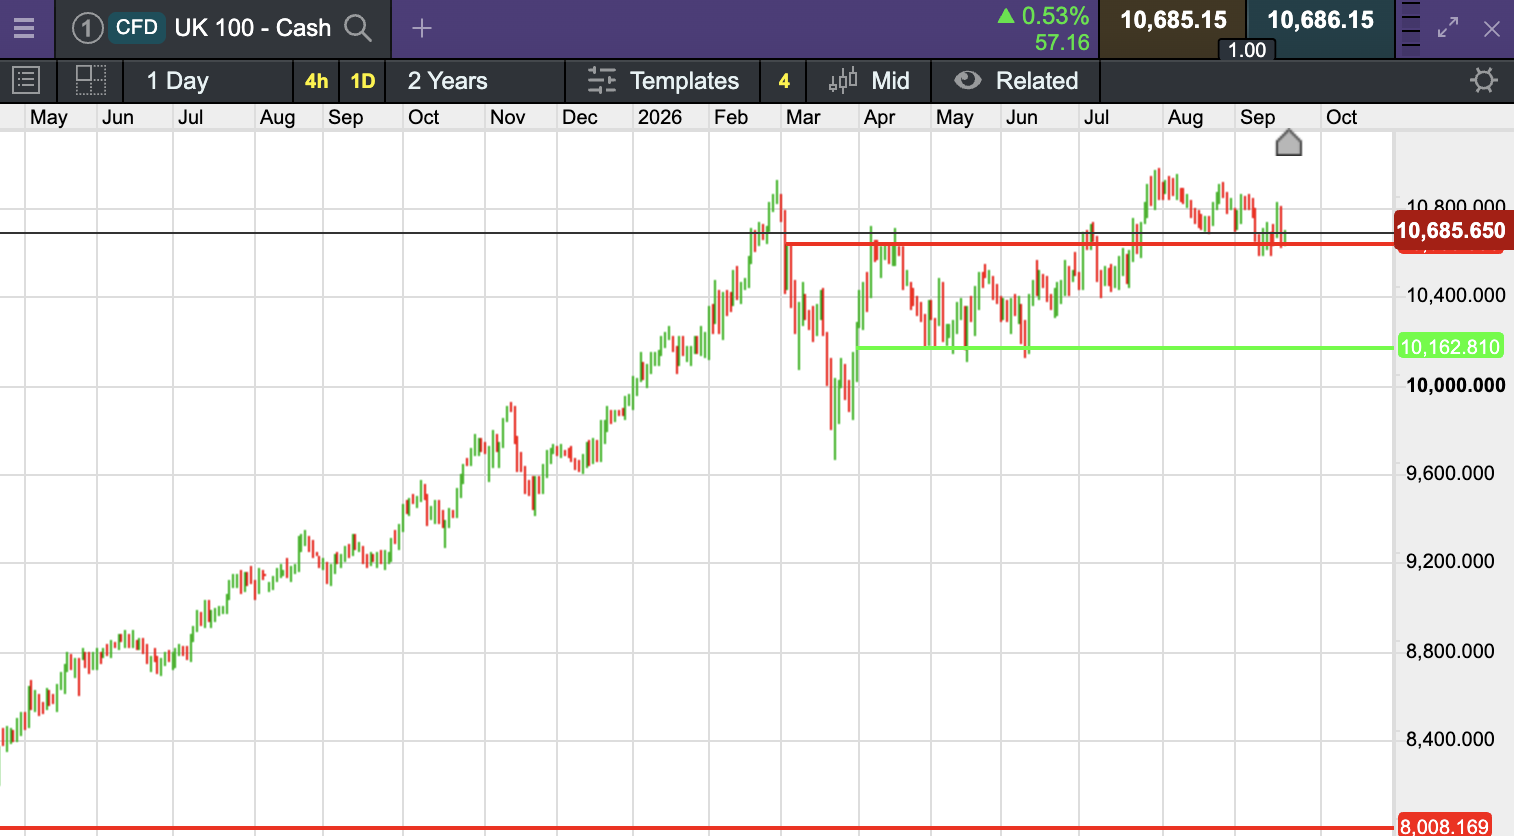
The UK 100 is called to open +29 points at at 10,688. Stocks in London are set to open higher on Monday, recovering a fraction of Friday’s slump, amid optimism over easing tensions between the US and China, ahead of a meeting between Donald Trump and Xi Jinping.
Futures indicate the UK 100 to open 29 points higher, 0.3%, at 10,688.73 on Monday. The index of London large-caps slumped 157.01 points, 1.5%, at 10,659.13 on Friday.
Wall Street closed the week mixed on Friday as investors continued to digest the Federal Reserve’s first interest-rate hike in three years, delivered on 16 September. The S&P 500 edged up 0.17% to 7,650.50 and the Nasdaq Composite rose 0.39% to 26,522.55, led by technology (+0.87%) and industrials (+0.47%), while the Dow Jones Industrial Average slipped 0.18% to 51,682.64 as rate-sensitive names lagged. The 10-year Treasury yield hovered near the 5% threshold, up around 5 basis points on the day, as traders weighed the chance of a further hike in October. Brent crude eased back from mid-week highs as fears of an imminent Strait of Hormuz disruption receded, though sources diverge materially on the exact weekend level (see Commodities, below) — a reminder that oil pricing has been unusually volatile around the Middle East tensions story.
In Asia, Tokyo’s cash market is shut for Japan’s “Silver Week” holiday run (21–23 September), so the Nikkei 225’s last print remains Friday’s close of 65,019, up 1.38%. Elsewhere in Monday’s session, South Korea’s Kospi led gains, up around 1.3% to near 6,983, Hong Kong’s Hang Seng added roughly 0.4–0.5% to around 24,850–24,867, and Shanghai’s Composite gained about 0.5% to near 3,931; Australia’s ASX 200 was little changed to slightly softer (sources put it at −0.03% to −0.15%). On the UK/European macro front, the Bank of England held Bank Rate at 3.75% on 17 September but three of nine MPC members voted for an immediate rise to 4%, against a backdrop of 3.1% UK CPI in August and stronger-than-expected UK retail sales (+0.5% month-on-month). There are no Fed, ECB or Bank of England decisions this week (next scheduled: Fed 28 October, ECB 29 October, BoE 5 November); the calendar is instead dominated by central bank speakers and Wednesday’s flash PMIs. Rightmove’s UK asking-price index, released Sunday evening, showed its first monthly rise since May (+0.7% month-on-month, −0.8% year-on-year).
Company News & Broker Comments:
Company News:
AstraZeneca and Daiichi Sankyo’s Enhertu (trastuzumab deruxtecan) has been recommended for approval in the European Union (EU) as a monotherapy for the adjuvant treatment of adult patients with resected HER2-positive breast cancer who have residual invasive disease after neoadjuvant taxane-based and HER2-targeted treatment.
Reporting Today:
UK
No noteworthy announcements
US
No noteworthy announcements
Reporting Tomorrow:
UK
Craneware (CRW) – Full Year Results
US
No noteworthy announcements
In Focus Today:
| Time (UK) |
Country |
Event |
Consensus / Prior |
| 02:15 |
China |
PBOC 1-Yr / 5-Yr Loan Prime Rate |
Unch. 3.00% / 3.50% |
| Overnight |
UK |
Rightmove House Price Index (Sep) |
Actual: +0.7% m/m, −0.8% y/y |
| 11:30 |
US |
Chicago Fed President Goolsbee speaks |
— |
| 16:00 |
Canada |
BoC Governor Macklem speaks |
— |
No FOMC, ECB or BoE decisions fall this week (next: Fed 28 Oct, ECB 29 Oct, BoE 5 Nov). Wednesday brings flash September PMIs; the week is otherwise light on hard data but heavy on central bank speakers.
This Week’s Ex-Dividends:
UK 100 companies going ex-dividend on 24th September 2026:
Standard Life
Computacenter
UK 250 companies going ex-dividend on 24th September 2026:
Pollen Street Group
Drax Group
Rightmove
GlobalData
Harworth Group
For any help you may require placing trades or in terms of market information, put a call in to our trading floor – it’s all part of the service.