Getting latest data loading
Home / Morning Report / Morning Report – 29th September 2026

This report is not a personal recommendation and does not take into account your personal circumstances or appetite for risk.

Morning Report - 29 September 2026

Company Ticker Close (GBX) % chg
Barratt Redrow BTRW 353.45 +14.43%
Howden Joinery Group HWDN 803.50 +5.73%
Kingfisher KGF 342.35 +4.17%
Airtel Africa AAF 307.60 +2.67%
abrdn Group ABDN 250.60 +2.04%
Company Ticker Close (GBX) % chg
Fresnillo FRES 2,743.00 −5.09%
Endeavour Mining EDV 4,325.00 −4.42%
Experian EXPN 2,517.00 −3.56%
Pershing Square Holdings PSH 3,630.00 −2.47%
Polar Capital Technology Trust PCT 684.00 −2.15%
Index Close % chg Session
UK 100 10,684.88 −0.10% Mon 28 Sep
S&P 500 7,683.69 −0.77% Mon 28 Sep
Nasdaq Composite 26,820.38 −0.92% Mon 28 Sep
Dow Jones Industrial Average 51,481.51 −0.67% Mon 28 Sep
DAX 25,374 −0.13% Mon 28 Sep
Commodity Price % chg As of / source
Gold, spot (US$/oz) 4,127 +0.30% Trading Economics, 29 Sep
Brent crude, front-month (US$/bbl) ~99.63 +1.8% AP wire, early 29 Sep
Copper, LME 3-month (US$/t) ~14,460 −0.18% Trading Economics (derived), 29 Sep
Silver, spot (US$/oz) 60.75 +0.21% Trading Economics, 29 Sep
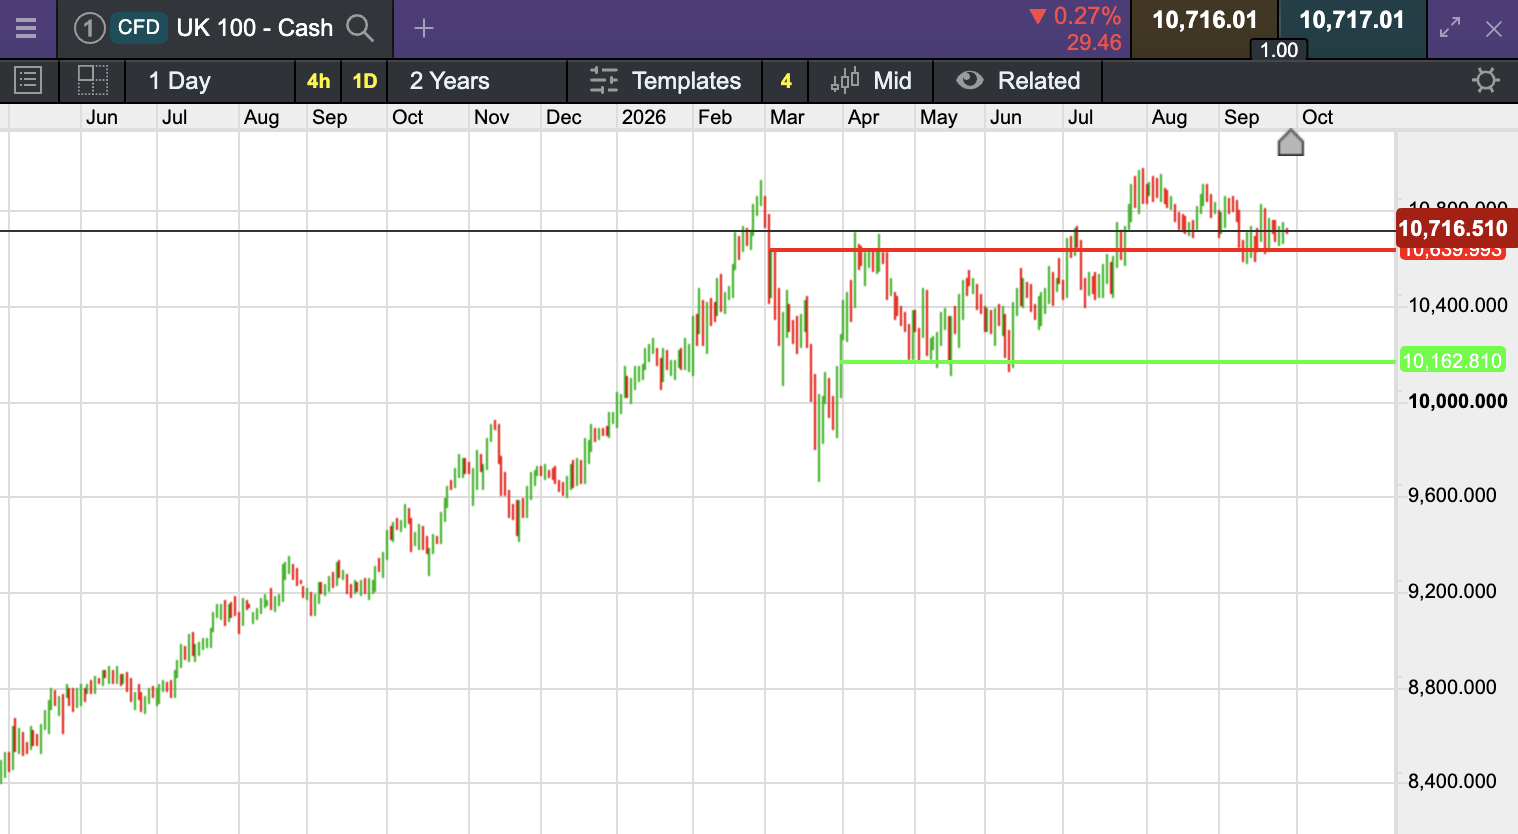
The UK 100 is called to open +48 points at at 10,732.  

1 Day; 2 Years

Click graph to enlarge

Markets Overview:


The UK 100 is called to open +48 points at at 10,732.  
Stocks in London are set to open slightly higher on Tuesday, as UK shop price inflation eased and investors digested an expected interest rate hike from the Reserve Bank of Australia.

Wall Street fell for a second straight session on Monday after President Trump rejected Iran’s latest proposal over the Strait of Hormuz, reviving fears of a Gulf oil-supply disruption. The S&P 500 slid 0.8% to 7,683.69, the Nasdaq Composite lost 0.9% to 26,820.38 and the Dow Jones Industrial Average fell 0.7% to 51,481.51, with only energy and healthcare holding up among sectors. The US 10-year Treasury yield pushed up to around 5.25–5.27%, its highest since 2007, adding further pressure to equity valuations. Oil jumped on the Iran headlines, though wire reports disagreed materially on the exact settlement level (estimates ranged from roughly $98 to $108 a barrel for Brent) — see the Commodities note below.

Asian markets were mostly lower in early Tuesday trade on the back of Wall Street’s losses and firmer crude: Japan’s Nikkei 225 fell around 1.2–1.4% to near 65,000, South Korea’s Kospi lost about 0.6% as chip stocks gave back some recent gains, and Hong Kong’s Hang Seng eased roughly 0.4–0.5% on continued weakness in Chinese tech names; Shanghai and Australia’s ASX 200 bucked the trend, both up around 0.1%. There are no Bank of England, Fed or ECB decisions this week — the BoE’s next MPC meeting is 5 November, the Fed’s is 27–28 October and the ECB’s is 28–29 October — but today brings UK mortgage and consumer credit data, Swiss and Spanish inflation prints, eurozone economic sentiment, and half-year/interim results from A.G. Barr, Carnival and Close Brothers Group.


Company News & Broker Comments:


Company News:

Astrazeneca are to invest $2bln in Summit therapeutics to accelerate development of Ivonescimap.


Reporting Today:


UK

Company Ticker Release
A.G. Barr BAG Half-year results
Carnival Corporation CCL Q3 results
Close Brothers Group CBG Full-year results


US

No noteworthy announcements

Reporting Tomorrow:


UK

Company Ticker Release
Greggs GRG Q3 trading statement


US

No noteworthy announcements

In Focus Today:

Time (UK) Region Release Prior / Consensus
05:30 (out) Australia RBA interest rate decision Held at 4.35% (in line)
~08:00 Switzerland KOF Leading Indicator Prior 106.7 / Cons. 105.8
~08:00 Spain Flash inflation, y/y Prior 4.3% / Cons. 4.0%
~09:30 UK Mortgage approvals & consumer credit n/a
~10:00 Eurozone Economic Sentiment Indicator Prior 98.4 / Cons. 97.5
~13:30 Canada Monthly GDP n/a
~15:00 US Conference Board consumer confidence; JOLTS job openings JOLTS prior 7.27m / Cons. 7.2m

This Week’s Ex-Dividends:


UK 100 companies going ex-dividend on 1st October 2026:

British American Tobacco

Smith & Nephew

Weir Group

F&C Investment Trust


UK 250 companies going ex-dividend on 1st October 2026:

Wickes Group

TP ICAP Group

Breedon Group

Kainos Group

Hunting

Morgan Sindall Group

Bodycote

Travis Perkins


For any help you may require placing trades or in terms of market information, put a call in to our trading floor – it’s all part of the service.


Back to Top

This research is produced by Accendo Markets Limited. Research produced and disseminated by Accendo Markets is classified as non-independent research, and is therefore a marketing communication. This investment research has not been prepared in accordance with legal requirements designed to promote its independence and it is not subject to the prohibition on dealing ahead of the dissemination of investment research. This research does not constitute a personal recommendation or offer to enter into a transaction or an investment, and is produced and distributed for information purposes only.


Accendo Markets considers opinions and information contained within the research to be valid when published, and gives no warranty as to the investments referred to in this material. The income from the investments referred to may go down as well as up, and investors may realise losses on investments. The past performance of a particular investment is not necessarily a guide to its future performance.

Spread bets and CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage.
Spread bets and CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 69% of retail investor accounts lose money when spread betting and/or trading CFDs with this provider. You should consider whether you understand how spread bets and CFDs work and whether you can afford to take the high risk of losing your money.
.