Markets Overview:
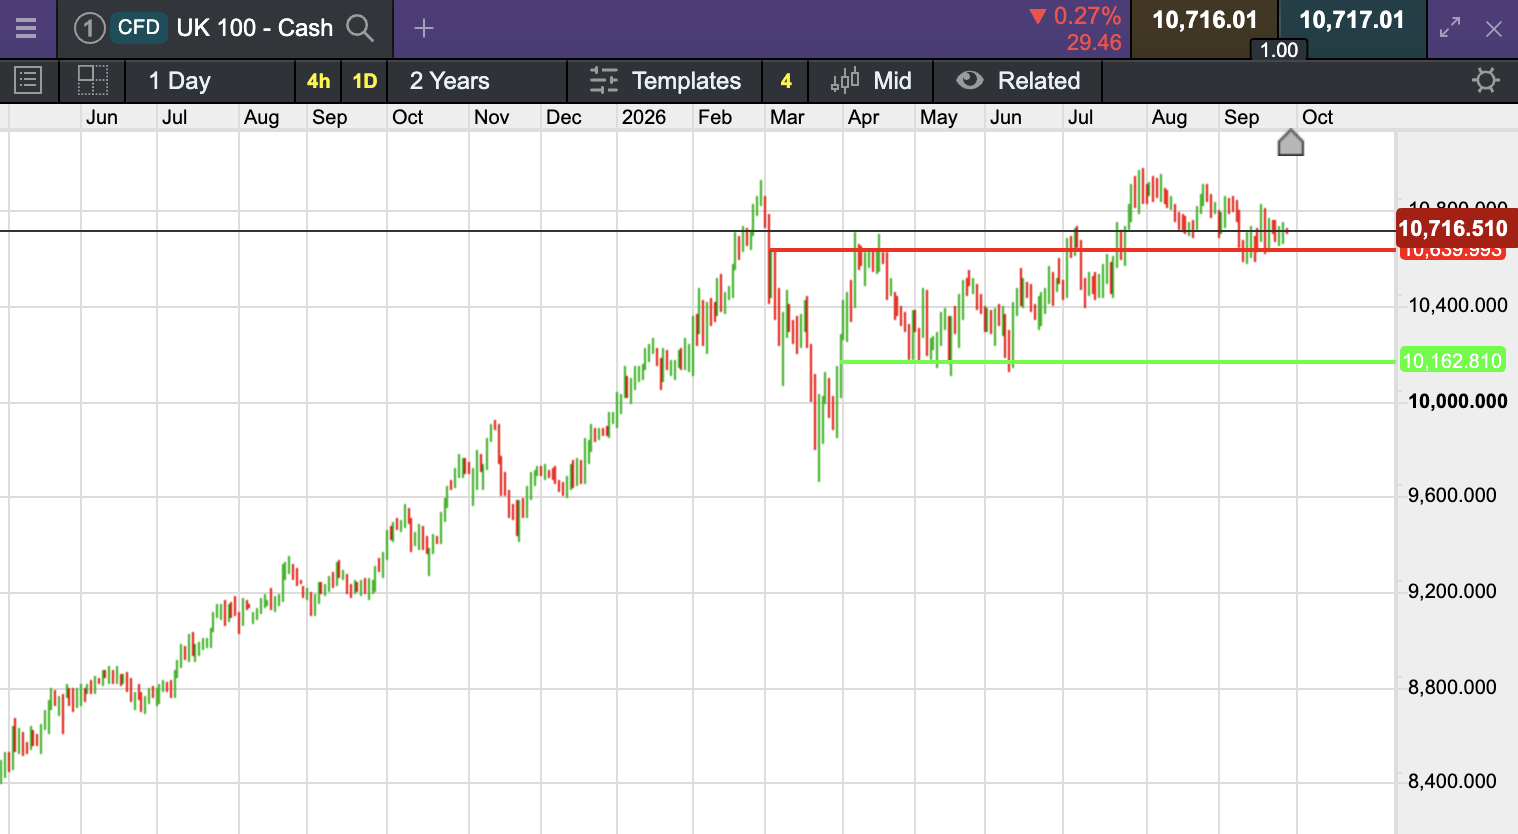
The UK 100 is called to open +26 points at at 10,721. Stocks in London are set to open higher on Monday, as oil prices rose after US President Donald Trump rejected an Iranian proposal for a seven-day truce that could have seen the Strait of Hormuz reopen.
Wall Street closed higher on Friday, with the Dow Jones Industrial Average up 0.93% to 51,828.62, the S&P 500 adding 0.51% to 7,743.41, and the Nasdaq Composite gaining 0.48% to 27,068.72 — the Dow’s gain snapped a three-week losing streak. Strength in tech and industrials, plus optimism that a Trump–Xi summit will preserve the US–China trade status quo, outweighed a further sell-off in bonds and a weak final University of Michigan consumer sentiment reading (48.1, a four-month low, on tariff and fuel-price worries). The US 10-year Treasury yield finished the week around 5.17–5.20%, close to its highest level since 2007, as inflation concerns tied to rising oil prices keep pressure on rate expectations. Brent crude eased about 2% on Friday to roughly $104/bbl on hopes that Iran might agree a deal to help reopen the Strait of Hormuz.
That hope unravelled over the weekend: President Trump publicly rejected Iran’s proposed seven-day roadmap for reopening the Strait on Saturday, and Tehran said it “will not back down.” Oil has reversed higher as a result — Brent was recently changing hands around $106–107/bbl, up roughly 2% — and this is the dominant overnight theme feeding into today’s European open. Asian markets were mixed: the Nikkei 225 was little changed, the ASX 200 added 0.3%, the Hang Seng rose 0.7%, while the Kospi fell 2.3% and the Shanghai Composite dropped 1.7%, with China also reporting industrial profit growth slowing to a year-to-date low. Closer to home, it is a quiet week for central banks — no BoE, Fed or ECB policy decisions are due — though several Bank of England officials speak this week (Dave Ramsden on quantitative tightening today) and the US data slate builds toward Friday’s non-farm payrolls, via Wednesday’s PCE inflation print and Thursday’s ISM manufacturing survey.
Company News & Broker Comments:
Company News:
Reporting Today:
UK
Tullow Oil (TLW) – Half Year Results
US
No noteworthy announcements
Reporting Tomorrow:
UK
Barr (A.G.) (BAG) – Q2 2027 Results
Card Factory (CARD) – Interim Results 2026
Close Brothers Group (CBG) – 2026 Preliminary Results
US
No noteworthy announcements
In Focus Today:
| Time (UK) |
Region |
Release |
Consensus / Prior |
| Overnight |
China |
Industrial profits (Aug, y/y) |
+4.2% (weakest monthly pace this year) |
| — |
UK |
No scheduled data release today |
— |
| 11:00 |
UK |
BoE’s Dave Ramsden speaks (quantitative tightening) |
— |
| 15:30 |
US |
Dallas Fed Manufacturing Index (Sep) |
Prior 11.6; consensus n/a |
| Later |
US |
Fed’s John Williams speaks (time tbc) |
— |
This Week’s Ex-Dividends:
UK 100 companies going ex-dividend on 1st October 2026:
British American Tobacco
Smith & Nephew
Weir Group
F&C Investment Trust
UK 250 companies going ex-dividend on 1st October 2026:
Wickes Group
TP ICAP Group
Breedon Group
Kainos Group
Hunting
Morgan Sindall Group
Bodycote
Travis Perkins
For any help you may require placing trades or in terms of market information, put a call in to our trading floor – it’s all part of the service.