Markets Overview:
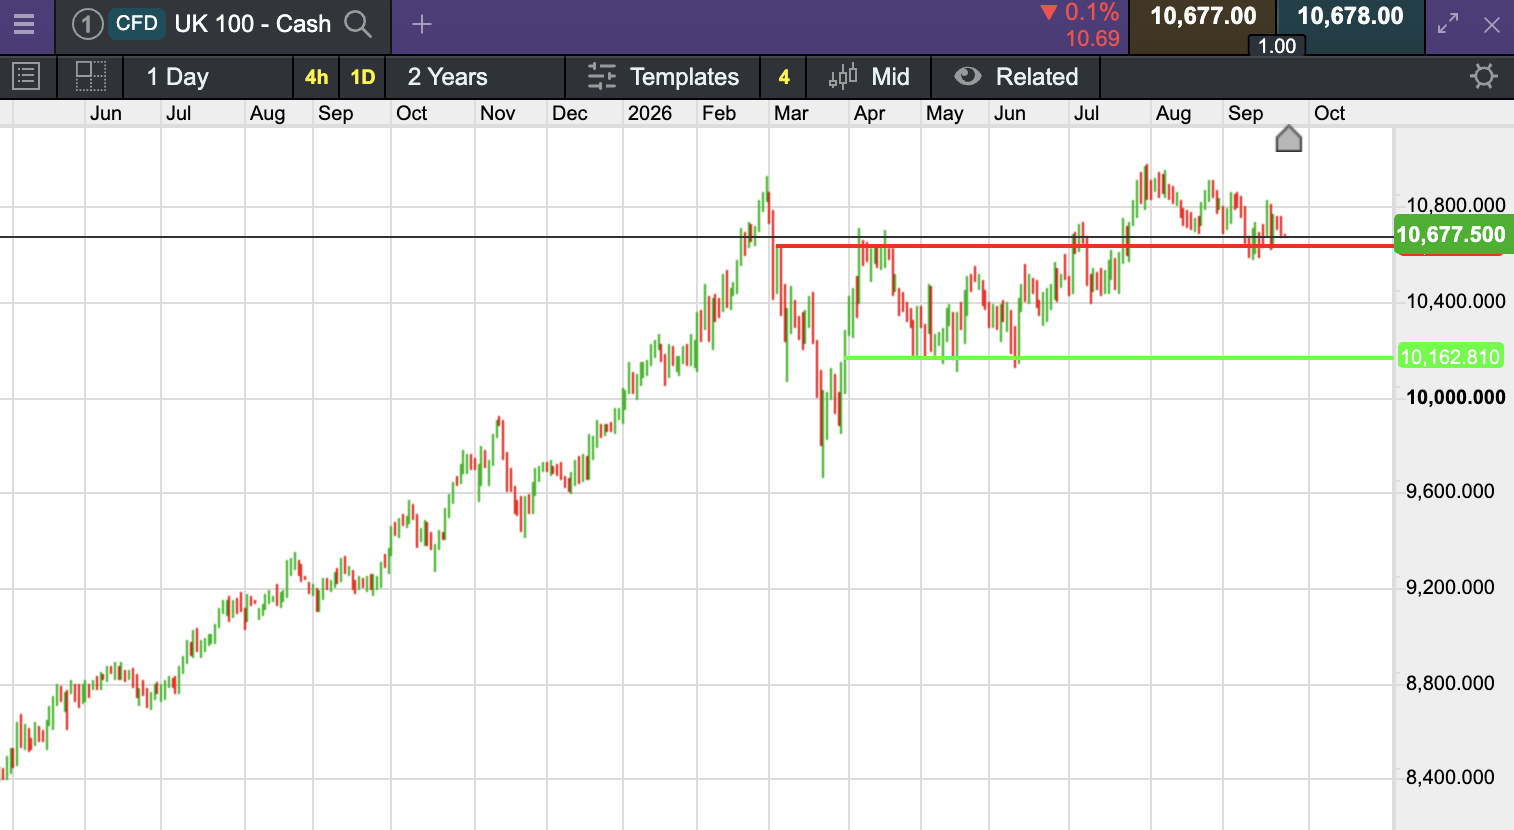
The UK 100 is called to open -20 points at at 10,685. Stocks in London are set to open marginally lower on Thursday as investors weighed a sell-off in US government bonds, firmer oil prices and reports the UK Treasury could opt for a smaller fiscal buffer at next month’s Budget.
Wall Street sold off on Wednesday as the sharpest bond-market move in months hit sentiment: the S&P 500 fell around 0.8% to roughly 7,701, the Dow shed about 0.7% to near 51,540, and the Nasdaq Composite dropped about 1.1% to close near 26,899, with more than 70% of NYSE-listed issues lower. The trigger was a surge in the US 10-year Treasury yield to 5.11%–5.12%, its highest since July 2007, after a stronger-than-expected flash S&P Global composite PMI (58.4 vs 55.3 forecast) and hawkish comments from Fed Governor Michael Barr on the need for further tightening; futures markets are now pricing roughly a 71% chance of another quarter-point hike in October. The 10-year yield was holding around the same level early Thursday.
Brent crude reversed sharply higher, up around 4.1% to near $103/bbl, as renewed fears over US-Iran tensions offset the diplomatic optimism that had driven a roughly six-session slide earlier in the week — a swing that itself has fed into the inflation narrative behind Wednesday’s bond sell-off. Asian markets were mixed overnight: Japan’s Nikkei 225 jumped about 1.4% to roughly 65,900 as it reopened after a public holiday, led by tech and AI names, while Hong Kong’s Hang Seng fell 0.3% to 24,752 (a second straight losing session) and Shanghai’s Composite dropped 0.9% to 3,899 on spillover from the global yield/dollar move; Australia’s ASX 200 fell 0.8% to 8,697 and South Korea’s Kospi extended a four-session winning run, +0.9% to 7,081 at Wednesday’s close. On the UK/European calendar, there is no Bank of England or ECB meeting this week (the BoE’s next decision is 5 November; the Fed’s next FOMC is 27–28 October), but today is unusually central-bank-heavy elsewhere, with Sweden’s Riksbank, the Swiss National Bank, Norges Bank and Mexico’s Banxico all due to announce policy, alongside Germany’s Ifo survey, US jobless claims, and continued focus on Chinese President Xi’s state visit to the US.
Company News & Broker Comments:
Company News:
Vistry Group reported a first-half adjusted loss before tax of £83.3 million for the period ended 30 June 2026, a significant shift from the £80.6 million profit in the prior year, driven by discounting to improve cash generation and £50 million in costs related to a strategic review. The company experienced an 8% decrease in total completions to 6,304 units and a 9% revenue decline to £1,703.3 million. Net debt increased to £468.8 million from £293.1 million. The company is repositioning itself as a smaller, more focused mixed-tenure housebuilder, targeting approximately 12,000 completions annually and aiming for a 60:40 split between partner-funded and open market sales, with a goal of achieving over 30% ROCE by FY31. The company also secured a £350 million direct grant award from the Social and Affordable Housing Programme.
Reporting Today:
UK
Raspberry Pi Holdings (RPI) – Interim Results
Halma (HLMA) – Trading Update
CVS Group (CVSG) – Preliminary Results
US
Costco Wholesale Corp (NASDAQ:COST) AMC
Reporting Tomorrow:
UK
No noteworthy announcements
US
No noteworthy announcements
In Focus Today:
| Time (UK) |
Country |
Release |
Consensus |
Prior |
| Overnight |
Japan |
Flash S&P Global PMI (Sep) |
n/a¶ |
n/a¶ |
| Overnight |
Australia |
Employment change (Aug) |
n/a¶ |
n/a¶ |
| 08:00 |
Germany |
Ifo Business Climate (Sep) |
89.0 |
88.8 |
| 13:30 |
US |
Initial jobless claims (w/e 19 Sep) |
201k |
196k |
Today’s Ex-Dividends:
UK 100 companies going ex-dividend on 24th September 2026:
Standard Life
Computacenter
UK 250 companies going ex-dividend on 24th September 2026:
Pollen Street Group
Drax Group
Rightmove
GlobalData
Harworth Group
For any help you may require placing trades or in terms of market information, put a call in to our trading floor – it’s all part of the service.