Markets Overview:
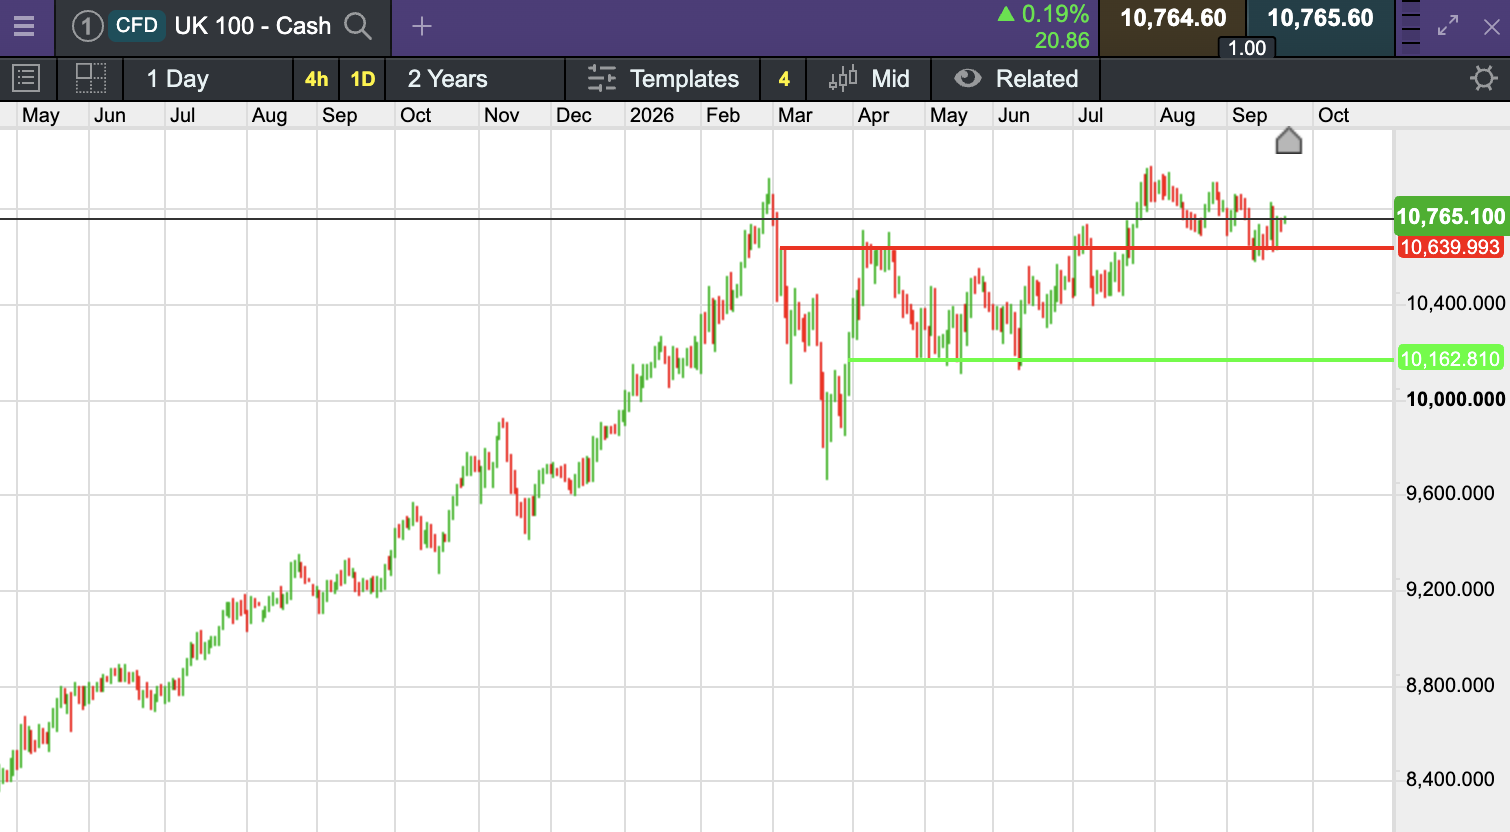
The UK 100 is called to open +55 points at at 10,763. Stocks in London are set to open higher on Wednesday as investors welcomed signs of renewed US-Iran diplomacy ahead of a fresh batch of flash PMI data from Europe, the UK and the US.
Wall Street closed mixed but firmer overall on Tuesday, with the Nasdaq Composite notching a fresh record close, up 0.45% to 27,244.28, as Meta Platforms’ new “Muse” AI agent topped app-store download charts and reignited enthusiasm for the AI trade across the “Magnificent Seven”. The S&P 500 was essentially flat at 7,764.64 (‑0.06 points), sitting roughly 0.4% below last month’s record high, while the Dow Jones Industrial Average slipped 0.36% to 51,863.69, weighed down by weakness in financials and defence names as markets continued to digest last week’s Federal Reserve meeting. The US 10-year Treasury yield held little changed around 4.96%, still close to the five-year highs briefly touched earlier this month, as investors awaited fresh jobs data and further Fed commentary. Brent crude was volatile, dipping intraday below $98/bbl for the first time since 8 September before paring losses to settle nearer $99/bbl (around ‑1% on the day), on hopes of progress toward reopening the Strait of Hormuz and easing US-Iran tensions; WTI fell a sharper 2.9% to $89.67.
Asian markets were mixed in early Wednesday trade. Tokyo’s Nikkei 225 remained shut for a run of Japanese public holidays (Respect for the Aged Day and the Autumnal Equinox, 21-23 September), leaving the index frozen at last Friday’s close of 65,019 (+1.38%). South Korea’s Kospi closed Tuesday up 0.15% at 7,017.91 after giving back a sharp early gain, while Wednesday’s session was still under way at the time of writing. Hong Kong’s Hang Seng was down around 0.9% intraday on Wednesday morning as investors took profits in technology names ahead of anticipated talks between the US and Chinese leaderships, and Australia’s ASX 200 and Shanghai’s Composite were both little changed / still trading as this report was compiled (see note under commodities/indices for timing). On the UK/European calendar, there are no Bank of England, ECB or Fed meetings this week — all three met earlier in September and next decisions are not due until late October/early November — but flash September PMIs for the UK, France, Germany and the Eurozone, plus a first look at US PMIs, are due today (see “In focus today” below).
Company News & Broker Comments:
Company News:
JD Sports reported a 19.7% drop in first-half profit on Wednesday, hurt by weakness in its key North American market, but maintained the full-year earnings outlook it downgraded last month.
Reporting Today:
UK
| Company |
Announcement |
| Ceres Power Holdings |
Half year results |
| JD Sports Fashion |
Half year results |
| Renishaw |
Full year results |
US
No noteworthy announcements
Reporting Tomorrow:
UK
| Company |
Announcement |
| Vistry Group |
Half year results |
| Halma |
Half year trading statement |
| CVS Group |
Full year results |
| Raspberry Pi Holdings |
Half year results |
| Mitchells & Butlers |
Trading statement |
| BioPharma Credit |
Half year results |
US
No noteworthy announcements
In Focus Today:
| Time |
Region / release |
Consensus |
Prior |
| ~07:15 |
France flash Manufacturing/Services PMI (Sep) |
n/a |
n/a |
| ~07:30 |
Germany flash Manufacturing/Services PMI (Sep) |
n/a |
n/a |
| 08:00 |
Eurozone flash Composite PMI (Sep) |
n/a |
n/a |
| 08:30 |
UK flash Manufacturing PMI (Sep) |
51.5 |
n/a |
| 08:30 |
UK flash Services PMI (Sep) |
52.0 |
52.8 (Aug) |
| 08:30 |
UK flash Composite PMI (Sep) |
52.3 |
52.5 (Aug, final) |
| 13:45 |
US flash Manufacturing PMI (Sep) |
53.6 |
53.9 (Aug) |
| 13:45 |
US flash Services PMI (Sep) |
55.8 |
56.5 (Aug) |
| 14:30 |
US EIA weekly crude oil inventories |
−0.6m bbl |
−0.64m bbl |
Tomorrow’s Ex-Dividends:
UK 100 companies going ex-dividend on 24th September 2026:
Standard Life
Computacenter
UK 250 companies going ex-dividend on 24th September 2026:
Pollen Street Group
Drax Group
Rightmove
GlobalData
Harworth Group
For any help you may require placing trades or in terms of market information, put a call in to our trading floor – it’s all part of the service.